STILL MAKING CAR PAYMENTS? YOUR LENDER DOESN'T HAVE TO BE THE REASON YOU KEEP A CAR YOU WANT TO SELL!
You've found a buyer for your car. Fantastic! There's just one little complication: your bank still has a financial interest in it.
Maybe you owe $4,000. Maybe it's $24,000. Either way, that outstanding loan doesn't automatically mean your vehicle is trapped in your driveway until the final payment. You can sell a car with a lien!
The important part is understanding how the loan gets paid and how ownership legally transfers.
What Exactly Is a Lien on a Car?
A lien is a lender's legal claim against your vehicle, usually because you financed its purchase. Until the debt is satisfied, that lender has rights connected to the title. [1]
Think of it this way: You get to drive the car, maintain it, insure it, and make those delightful monthly payments. But your lender still has a seat at the table when it's time to sell. A lien doesn't prohibit every sale. It means the payoff and title paperwork must be handled correctly.
First, Find Out What You Actually Owe!
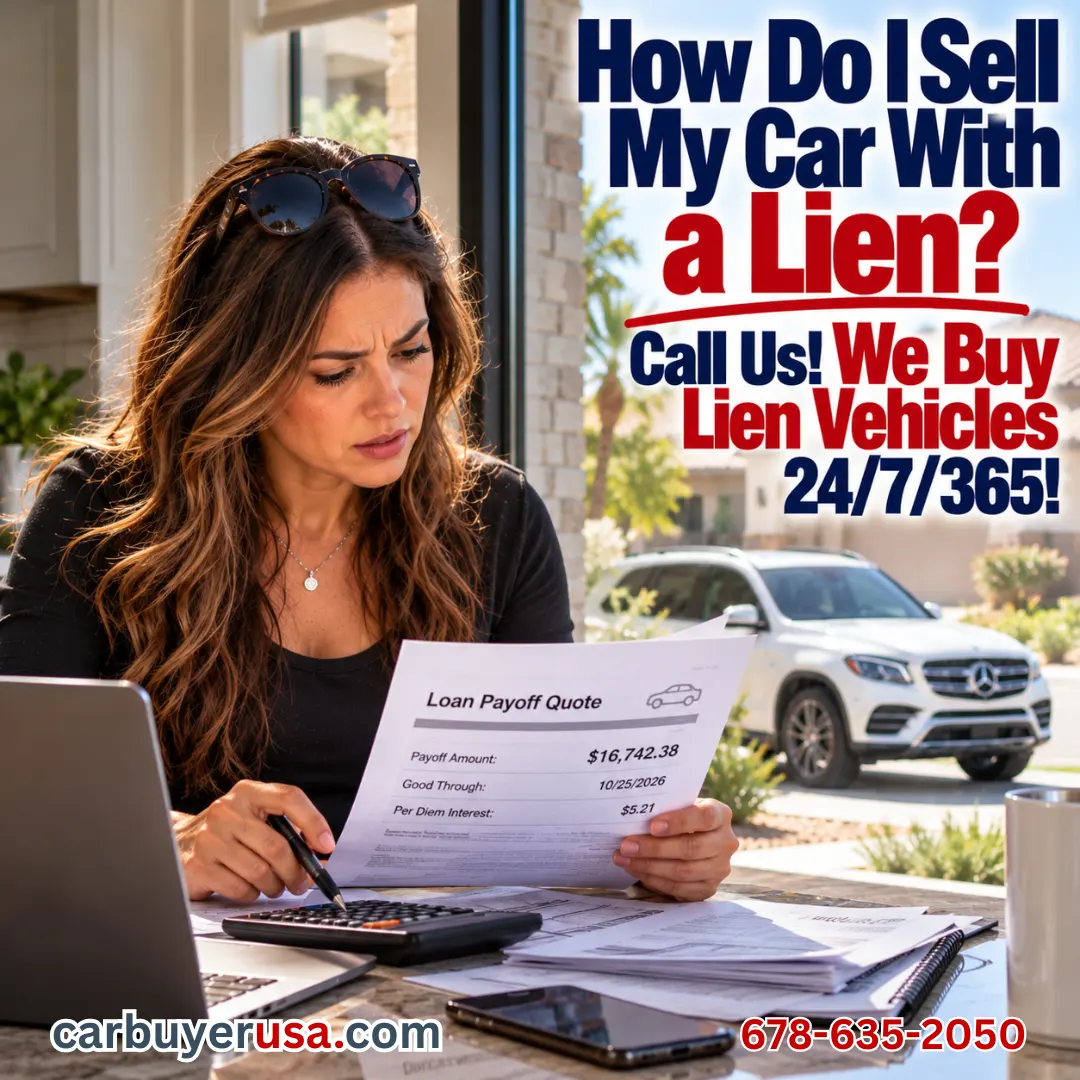
Don't rely on the balance displayed on your latest statement. Request an official loan payoff quote from your lender. The Consumer Financial Protection Bureau explains that a payoff amount can differ from your displayed loan balance because of accrued interest, fees, or other charges. [2]
Ask for the payoff amount, its expiration date, payment instructions, and information about how the lender releases its lien. This is particularly important when interest accrues daily. A payoff quote that's already expired can create an unexpected shortage.
What If I Owe More Than My Car Is Worth?
Here's where things get interesting. Your vehicle's value and your loan balance are two completely different numbers.
Your Situation |
Illustrative Example |
What It Means |
|---|---|---|
Positive equity |
Offer: $18,000; payoff: $13,000 |
Approximately $5,000 remains for you |
Break-even |
Offer: $15,000; payoff: $15,000 |
Sale proceeds cover the loan |
Negative equity |
Offer: $12,000; payoff: $16,000 |
Approximately $4,000 must be covered |
Payoff quote expires |
Additional interest or fees become
due |
Updated payoff may be required |
Figures are hypothetical and exclude possible transaction costs.
If your car is worth more than you owe, that's positive equity. After the lender receives the payoff, the remaining proceeds may go to you.
If you owe more than the selling price, that's negative equity. The difference generally must be resolved before the lien can be cleared. [2]
Selling your car doesn't magically erase the remaining loan balance. Wouldn't that be convenient?
How Does the Lender Get Paid?
A lien vehicle sale generally involves confirming the payoff, arranging payment to the lender, obtaining lien-release documentation, and completing the ownership transfer.
The exact procedure depends on the lender, state title rules, and whether the title is electronic or printed.
Some lenders release liens electronically, while others issue signed paperwork or release a paper title. State motor vehicle agencies establish the applicable title requirements. [3]
Before signing anything, confirm who pays the lender, how any remaining proceeds are distributed, and what documentation completes the transfer.
Can I Sell My Car If I Don't Have the Title?
Possibly! Many lenders hold the title or maintain an electronic lien record while a vehicle loan remains outstanding. Not having a paper title in your glove compartment doesn't necessarily mean something is wrong.
However, you can't simply ignore the lender and hand over the keys. The lien must be addressed, and the title transferred according to applicable state procedures.
Why Choose CarBuyerUSA for a Lien Vehicle?
Selling privately can become complicated when buyers discover a lender is involved. They may worry about payment security, title delays, or whether the seller can legally transfer ownership.
CarBuyerUSA works with vehicle owners across the country who want to explore selling a car that still has an outstanding loan.
Instead of waiting until your last payment, you can discuss your vehicle's details, lender information, and current payoff to determine your available options. Start at CarBuyerUSA.com with a 20-second vehicle valuation. No name, email address, phone number, or VIN is required to begin.
For lien vehicles, additional information and lender coordination will be necessary before a purchase can be finalized.
STILL OWE MONEY ON YOUR CAR? DON'T ASSUME YOU HAVE TO KEEP IT!
Contact CarBuyerUSA and find out whether your financed vehicle qualifies for an offer. We're here for sellers exploring their options 24/7/365!
FOOTNOTES & SOURCES
[1] Utah Division of Motor Vehicles — Liens. Explains the lender's legal interest in a financed vehicle and lien-release procedures.
https://dmv.utah.gov/register/liens/
[2] Consumer Financial Protection Bureau — Should I Trade In My Car If It's Not Paid Off? Explains payoff quotes, positive and negative equity, and the financial implications of an outstanding loan.
https://www.consumerfinance.gov/ask-cfpb/should-i-trade-in-my-car-if-its-not-paid-off-en-2045/
3] Georgia Department of Revenue — How to Release a Lien and Security Interest on a Title. Describes lender releases, electronic liens, and title documentation.
https://dor.georgia.gov/how-release-lien-and-security-interest-title
Lien-release procedures vary by state and lender. Vehicle eligibility, payoff arrangements, and final offers require individual confirmation.